Beed’s take on the market: July 24 to August 21, 2026
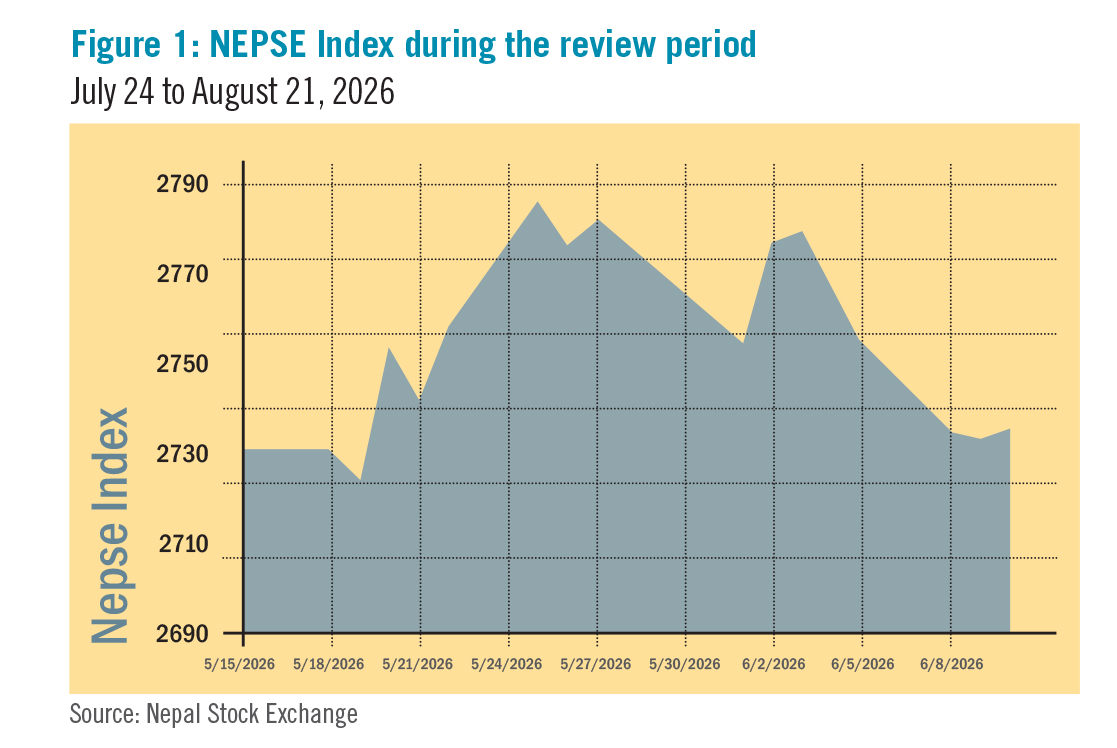
The Nepal Stock Exchange (NEPSE) index decreased significantly by 115.88 points (-4.24%) to close at 2,618.72 points during the review period from July 24 to August 21. The index declined continuously since the start of the review period and ultimately closed at 2,618.72 points. Market turnover increased marginally by 6.02%, compared to a 20.21% increase in the previous review period. The significant decrease in the index, coupled with an increase in turnover, indicates deteriorating investor confidence during the period. (See Figure 1)
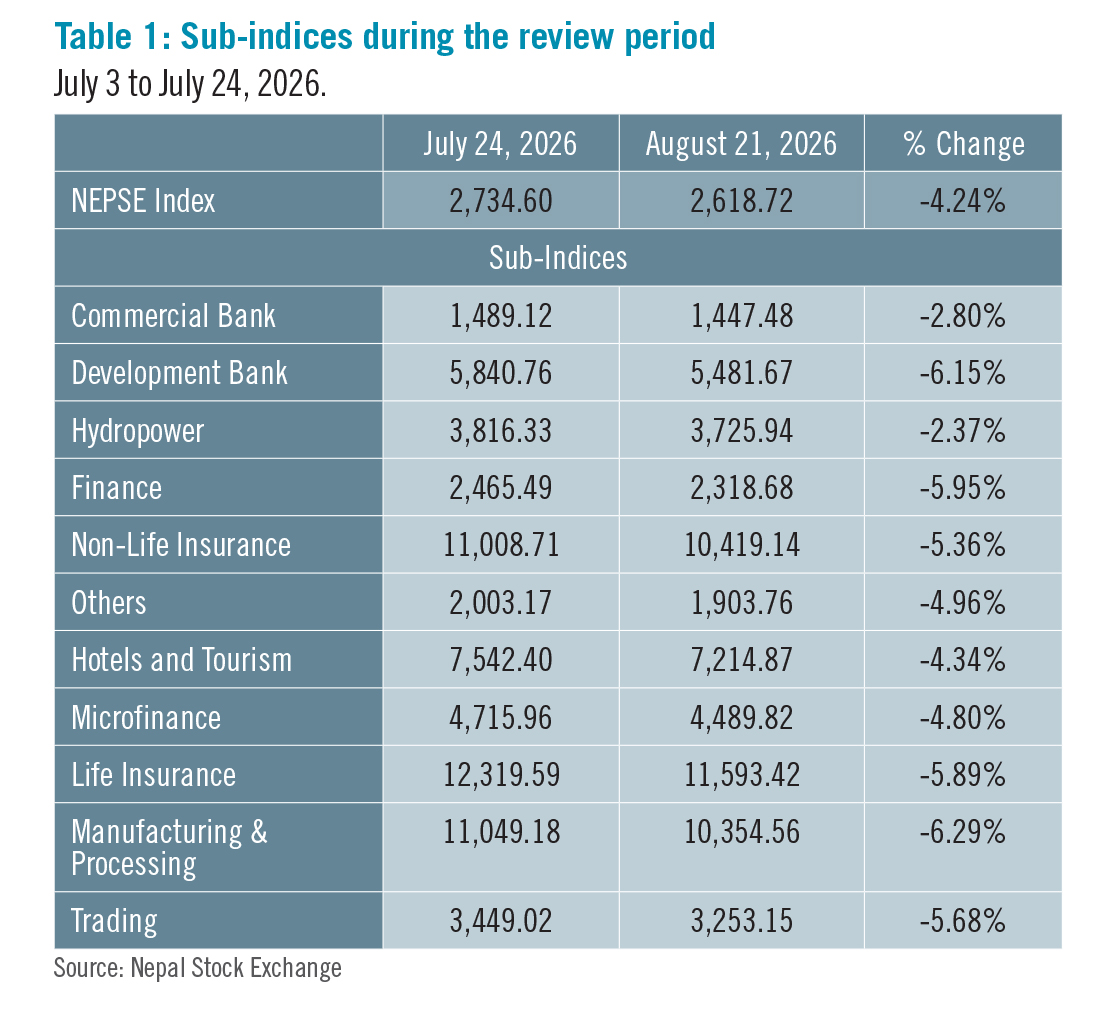
During the review period, all 11 sub-indices recorded losses. The Manufacturing and Processing, Development Bank and Finance sub-indices recorded the steepest decline whereas the Commercial Bank and Hydropower sub-indices experienced comparatively modest losses.
The Manufacturing and Processing sub-index recorded the steepest decline of 6.29%, due to declines in prices of Reliance Spinning Mills (-Rs 719), Sagar Distillery (-Rs 235) and SY Panel Nepal (-Rs 164). The Development Bank sub-index fell by 6.15% led by decline in Corporate Development Bank (-Rs 577), Salapa Bikas Bank (-Rs 256) and Green Development Bank (-Rs 118). The Finance sub-index dropped 5.95%, with losses posted in Best Finance Company (-Rs 59), Central Finance (-Rs 58.2) and Manjushree Finance (-Rs 49).
Similarly, Life Insurance sub-index declined by 5.89%, due to losses in Guardian Micro Life Insurance (-Rs 161.5), Crest Micro Life Insurance (-Rs 88.9) and Nepal Life Insurance (-Rs 52). Meanwhile, Trading sub-index fell 5.68%, as the share price of Bishal Bazar Company (-Rs 275) declined. Non-Life Insurance sub-index dropped by 5.36%, driven by losses in Rastriya Beema Company (-Rs 530.4), Nepal Micro Insurance Company (-Rs 107) and NLG Insurance (-Rs 45.1).
Others sub-index declined by 4.96%, led by losses in Muktinath Krishi Company (-Rs 260), Jhapa Energy (-Rs 176.1) and Pure Energy (-Rs 101). The Microfinance sub-index fell 4.80%, with steep losses seen in Aatmanirbhar Laghubitta Bittiya Sanstha (-Rs 1,519), Mahila Laghubitta Bittiya Sanstha (-Rs 555.7) and Upakar Laghubitta Bittiya Sanstha (-Rs 235). The Hotels and Tourism sub-index dropped by 4.34% weighed down by declines in Hotel Forest Inn (-Rs 117), Bandipur Cablecar and Tourism (-Rs 86.1) and Kalinchowk Darshan (-Rs 50.6).
The Commercial Bank sub-index recorded a more modest decline of 2.80%, due to losses in NIC Asia Bank (-Rs 30.2), Agricultural Development Bank (-Rs 19) and Prabhu Bank (-Rs 16.9).
Finally, the Hydropower sub-index recorded the smallest decline of 2.37%, with losses in Kalinchowk Hydropower (-Rs 217), Suryakunda Hydro Electric (-Rs 167.9) and Appolo Hydropower (-Rs 167). (See Table 1)
News and Highlights
Amid a decline in capital market indices, the Securities Board of Nepal (SEBON) has unveiled a series of policy papers, draft regulations and amendments aimed at deepening and modernising Nepal’s capital market.
To begin with, SEBON unveiled the White Paper on the Development of Nepal’s Primary Capital Market, 2026, outlining a three-phase reform plan for Nepal’s primary capital market. The first phase proposed policy and legal reforms, including amendments to relevant laws and a review of the book-building system. The second phase proposed institutional and technological upgrades, including a Digital Initial Public Offering (IPO) Platform, Electronic Know Your Customer (e-KYC), RegTech and SupTech systems. Finally, the third phase proposed fully market-based price discovery and greater participation of Qualified Institutional Buyers and anchor investors.
The white paper also called for strengthening the due diligence responsibilities of issue and sales managers, auditors, and credit rating agencies to improve accountability in public issuances.
Following this, SEBON approved and implemented the Primary Capital Market Reform Policy 2026 aiming to modernise the primary market and improve access of industries, infrastructure, innovation, SMEs and green and sustainable projects to long-term financing. The policy proposed fully digital, transparent and time-bound public issuance processes along with market-based pricing with greater participation of eligible institutional and strategic investors. The framework further includes expanding capital market access for technology-based and high-growth enterprises, attracting international investors, and gradually institutionalising Environmental, Social and Governance (ESG) disclosures in line with international practices. It also emphasised stronger regulation, corporate governance, investor protection and monitoring of funds raised through public offerings.
In addition to these reforms, SEBON also amended the Securities Registration and Issue Regulations, 2016, to allow companies jointly established by the government and non-resident Nepalis to raise up to 85% of their paid-up capital through public share offerings.
The draft Margin Lending Transaction Regulations, 2026, was also unveiled by SEBON, aiming to strengthen the regulatory framework for margin lending and investor protection. The draft retains the existing 30% initial margin and 20% maintenance margin requirements, meaning investors must finance at least 30% of a transaction from their own funds, with the remainder financed through margin lending. It also requires separate margin accounts, daily collateral valuation, margin calls, and adequate capital and liquidity from lenders. Margin lenders would be allowed to finance up to five times their certified net worth.
Apart from equity instruments, SEBON also gave attention to debenture instruments and published the draft Debenture Registration and Issue Regulations, 2026. The draft aims to diversify funding sources, improve market liquidity, strengthen risk management and align the domestic bond market with international practices. It also proposes allowing eligible corporate companies, in addition to banks and financial institutions, to raise long-term capital through the issuance of bonds and debentures.
Outlook
The review period ended on a weak note as the index fell to 2,618.72 points, with all 11 sub-indices posting losses and turnover rising only marginally. Nevertheless, SEBON’s reform agenda, covering primary market modernisation, margin lending, and debenture regulations, offers a constructive path forward for market development and investor protection. Although near-term sentiment remains cautious, timely implementation of these reforms could ultimately pave the way for the next phase of growth in Nepal’s financial market.
This is an analysis from beed Management. No expressed or implied warranty is made for the usefulness or completeness of this information, and no liability will be accepted for the consequences of actions taken based on this analysis.